
Tax News November 2026
Welcome to Tax News
Subscribe to get monthly updates on tax laws, policies, and events.
Overview
Tax News is a monthly online publication to inform tax professionals, taxpayers, and business owners about state income tax laws; Franchise Tax Board regulations, policies, and procedures; and events that may impact or provide valuable information for the tax professional community.
We also periodically release Tax News Flashes to quickly notify subscribers of urgent time-sensitive information.
In this edition
- New Secure Web Internet File Transfer (SWIFT) Templates
- 2026 Eligible Transmission Project Tax Credit (ETPTC) Available
- California Excess Business Loss Adjustments
- The 15-Day Rule for New Businesses
- Enhanced Tax Professional Hotline Support: Five-Account Assistance for Tax Practitioners
- Internal Revenue Service (IRS) Updates
- Ask the Advocate: Farewell
New Secure Web Internet File Transfer (SWIFT) Templates
SWIFT is the secure file transfer system external customers use to submit confidential information to FTB via the Internet. SWIFT uses Axway’s Secure Transport software. Transmitters should use SWIFT for all Internet file transfers.
Beginning Thursday, November 5, 2026, SWIFT users must use the new SWIFT templates when submitting Form 592 Resident and Nonresident Withholding Statement, 592-F Foreign Partner or Member Annual Return, and Form 593 Real Estate Withholding Statement. The templates ensure appropriate information is included in your submission.
To obtain a copy of the templates send an email request to wscs.swift@ftb.ca.gov.
We added several new warning and error codes along with information on how to correct errors to ensure the most accurate information is included.
The Field Name, Field Specifications, and Descriptions within the file have been updated to ensure users submit the required information to process the forms.
For more information on SWIFT for Resident, Nonresident, and Real Estate Withholding, refer to the user guide: FTB 923, Secure Web Internet File Transfer (SWIFT) Guide for Resident, Nonresident, and Real Estate Withholding or visit our website at ftb.ca.gov and search for SWIFT.
2026 Eligible Transmission Project Tax Credit (ETPTC) Available
ETPTC is a new tax credit established by California Senate Bill 254 in September 2025. The bill’s purpose is to incentivize investments in the development of transmission projects to further California’s clean energy goals.
Who Can Qualify?
ETPTC is available to qualified taxpayers with eligible transmission projects selected by the Transmission Infrastructure Accelerator and approved for financial assistance by the California Infrastructure and Economic Development Bank (“IBank”).
A Qualified Taxpayer means a taxpayer that is a participating party engaged in business or operations within the state and that applies for financing from IBank. A qualified taxpayer could be any person, company, corporation, association, state, or municipal governmental entity, partnership, firm, or other entity or group of entities.
Credit Overview
- The credit is equal to 20 percent of the qualified expenditure paid or incurred by the qualified taxpayer during the taxable year.
- Qualified expenditures include costs for planning, design, engineering, permitting, construction and equipment directly related to the eligible transmission project, as well as qualifying employee wages subject to California withholding for services directly related to that project.
- The credit amount is not to exceed $20,000,000 per qualified taxpayer per taxable year and is applied to the net tax.
- The credit is available for taxable years beginning on or after January 1, 2026, and before January 1, 2036.
- Unused credit can be carried over to the following taxable year and the succeeding seven taxable years, until exhausted.
- Claiming the credit reduces otherwise allowable deductions by the expenditures used to calculate it and prohibits a return on equity for the credit portion of the eligible transmission project.
Refer to California Revenue and Taxation Code (RTC) Sections 17053.40 and 23640 for more information.
Credit Assignment
A credit or carryover earned by members of a combined reporting group may be assigned to an affiliated corporation that is a member of the same combined reporting group that meets the provisions of an eligible assignee. The eligible assignee is treated as if it originally generated the assigned credit. Any credit limitations or restrictions that applied to the eligible assignor will also apply to the eligible assignee. For more information refer to Credit Assignments under RTC Section 23663.
For information about qualifying for the ETPTC, go to IBank.
For questions about claiming the credit, you may contact us at FTBETPTC@ftb.ca.gov.
California Excess Business Loss Adjustments
Section 70601 of the One Big Beautiful Bill Act (Act) (P.L. 119-21) enacted on July 4, 2025, amended Internal Revenue Code section 461 to make the business losses limitation permanent.
An excess business loss occurs when a taxpayer’s business deductions are greater than the taxpayer’s total business income or gains plus the allowed threshold. For federal tax purposes, for tax years beginning after December 31, 2026, individuals and other noncorporate taxpayers can deduct up to $256,000 of business losses, or $512,000 for married couples filing jointly. Any losses above these limits cannot be deducted that year. Instead, they are carried forward as net operating losses (NOLs).
This Act also changed how the loss limitation is adjusted for inflation. These adjustments apply to tax years beginning after December 31, 2025, and use the 2024 calendar year as the starting year for the cost-of-living adjustment.
California has modified conformity to IRC section 461(l) as specified in RTC section 17560.5 and does not conform to the changes made by P.L. 119-21. Also, California has different rules for the excess business loss limitation under IRC section 461(l) for tax years beginning after December 31, 2018. For California, excess business losses are carried forward under section 461(l), rather than treated as NOL carryforwards under IRC section 172.
The 2026 California excess business loss adjustment amounts are $320,000 for single or married/RDP filling separately filers and $640,000 for married/RDP taxpayers filing jointly. These amounts will be included in future FTB indexing memorandum publications.
The 15-Day Rule for New Businesses
With the end of the year quickly approaching, this is a good time to discuss the 15-day rule with your clients. The 15-day rule states a business entity (limited partnership, limited liability partnership, limited liability company, or corporation) is not required to file a tax return or subject to the taxes (and fees, if applicable) imposed on the business entity, including the $800 annual minimum tax, if it meets both of the following:
- The business entity did no business in California during the taxable year, and
- The business entity’s taxable year is 15 days or less
For example, if a business entity who files on a calendar year basis is formed on or after December 17, and does no business for the remainder of the year, then it may not have to file a tax return and/or pay the $800 annual minimum tax for that short taxable year.
Additionally, if the business entity meets the 15-day rule and is not required to file a tax return, this short period is not considered the first taxable year. The first taxable year will be the following year.
For example, if a corporation filing on a calendar year basis incorporates on December 20, 2026, and does not conduct business from December 20, 2026, through December 31, 2026, then it meets the 15-day rule and is not required to file a 2026 tax return. The corporation’s first taxable year will start on January 1, 2027.
For more information on the 15-day rule, go to Limited Liability Company Filing Information Publication, and Guide for Corporations Starting Business in California.
Enhanced Tax Professional Hotline Support: Five-Account Assistance for Tax Practitioners
To better serve tax practitioners and the customers they support, we are expanding hotline assistance to help resolve more payment verification needs in a single call.
Our current process allows for hotline agents to provide assistance for three payment verifications per call, except during designated peak periods when this limit would increase to five payment verifications per call.
The Hotline Leadership team conducted a thorough review of its support procedures and will implement a transition from three-account to five-account assistance for tax practitioners per call during a pilot period of October 12026, through March 15, 2027.
This change is intended to enhance customer satisfaction for tax practitioners to receive timely, convenient support and resolve more payment verification needs in a single call. We will monitor the pilot through March 15, 2027, to assess its impact on the customer experience and evaluate whether to continue the process.
Internal Revenue Service (IRS) Updates
We partnered with the IRS to provide monthly articles to assist our tax professional and small business communities and are excited to share this information; however, questions about the content should be directed to the IRS.
IRS reminder: Year-round tax planning can make filing easier
IR-2026-128, Oct. 23, 2026 — The IRS encouraged taxpayers to take simple steps now to make filing easier and avoid tax-time surprises next year.
IR-2026-126, Oct. 22, 2026 — The Department of the Treasury and the IRS issued two revenue procedures that update the correction program for employee retirement plans and create one for Individual Retirement Accounts.
IRS reminder: Take steps now to protect tax information
IR-2026-127, Oct. 22, 2026 — The IRS reminded taxpayers to protect their information from tax-related identity theft by safeguarding their IRS online-account credentials and obtaining an Identity Protection PIN.
Temporary reporting and recordkeeping relief for certain fuel uses
IR-2026-125, Oct. 21, 2026 — The IRS announced temporary administrative relief from reporting and recordkeeping requirements relating to taxes imposed by section 4041(a) of the Internal Revenue Code.
IR-2026-123, Oct. 16, 2026 — The IRS has already begun issuing refunds to more than 50,000 taxpayers who benefited from the adoption tax credit carryforward and expects the refund process for most eligible taxpayers to be complete by the end of the year.
IR-2026-124, Oct. 16, 2026 — The IRS announced Tax Professional Awareness Week, taking place the week of October 19th, which will feature webinars and practical tools to help tax professionals prepare for the upcoming filing season, support accurate tax return preparations and protect taxpayer information.
Treasury and IRS Move to Protect Health Care Benefits for Eligible Americans
IR-2026-121, Oct.14, 2026 — The U.S. Department of the Treasury and the IRS issued proposed regulations to implement President Trump’s Working Families Tax Cuts reforms to the Premium Tax Credit (PTC), a refundable tax credit that helps eligible American taxpayers afford health insurance purchased through the Health Insurance Exchanges.
IRS highlights partnership with UK tax authority’s new whistleblower program
IR-2026-120, Oct. 7, 2026 — The IRS highlighted its partnership with the United Kingdom’s whistleblower program, which drew upon the IRS Whistleblower Office’s expertise to quickly get established.
IRS reminder: Cybersecurity Awareness Month offers simple steps to protect tax data
IR-2026-119, Oct. 2, 2026 — The IRS encouraged taxpayers to take simple steps to strengthen online security during Cybersecurity Awareness Month.
IR-2026-117, Oct. 1, 2026 — The Department of the Treasury and the IRS issued proposed regulations to implement the new Federal Scholarship Tax Credit under section 25F, commonly known as the Education Freedom Tax Credit, the first federal tax credit supporting private contributions for K-12 scholarships.
The IRS seeks community partners and volunteers to support free tax services
IR-2026-118, Oct. 1, 2026 — The IRS’s Volunteer Income Tax Assistance (VITA) and Tax Counseling for the Elderly (TCE) programs are seeking volunteers and community partners to help provide free tax preparation services during the upcoming filing season.
Ask the Advocate: Farewell
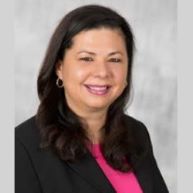
Angela Jones, Taxpayers’ Rights Advocate
As I retire, I leave with tremendous gratitude for my Franchise Tax Board (FTB) colleagues, the dedicated Taxpayers’ Rights Advocate’s Office “Small yet mighty Team”, and for each of you who has partnered with us in serving California taxpayers.
I find myself reflecting not only on the work accomplished, but on the people and partnerships that made that work meaningful. Among those I am especially grateful for is the tax practitioner community.
Serving as the FTB Taxpayers’ Rights Advocate has been one of the greatest honors of my career. At the heart of this role is a simple but important responsibility: to ensure taxpayers have a voice, that their rights are respected, and that when our tax system is not working as it should, someone is listening. You have been essential partners in that responsibility.
Tax practitioners occupy a unique place in our tax system. You are often the person sitting beside a taxpayer to help them understand a notice, ensure they file timely accurate tax returns, and that they fully understand their tax payment obligations.
Practitioners have helped the Taxpayers’ Rights Advocate’s Office identify systemic issues, unintended consequences, and gaps in tax administration. Your feedback matters because one taxpayer’s problem may signal an issue affecting many others.
Your willingness to speak up and to work collaboratively with us toward solutions has made the tax system better.
I am especially grateful for the relationships we have built through our liaison meetings (CSEA and CalCPA), outreach and education efforts, professional organizations, conferences, Taxpayer Bill of Rights hearings, and the many conversations that occurred simply because someone cared enough about a taxpayer or an issue to pick up the phone or send an email.
We have not always agreed, but effective advocacy requires communication, mutual respect, active listening, and a shared commitment. I value practitioners who thoughtfully challenge FTB, ask difficult questions, and keep taxpayers’ experiences at the center of the discussion. That partnership has strengthened our work.
Throughout my public-service career, I have strived to help taxpayers understand the complexity of the tax system, and the practitioner community helps FTB meet that responsibility.
Although I am retiring from my official role, I will carry with me the relationships, lessons, challenges, laughter, and sense of purpose that have defined this work. Most of all, I will carry the privilege of knowing that, together, we made a difference in the lives of taxpayers. I am also excited for you to work with FTB’s new Taxpayers’ Rights Advocate who will be announced next Tax News edition. You will enjoy working with the new Advocate.
Thank you for your trust. Thank you for your candor. Thank you for your partnership and collaboration. And thank you for the work you do every day on behalf of California taxpayers.
It has truly been an honor to serve.
With gratitude,
Angela Jones
Taxpayers’ Rights Advocate